
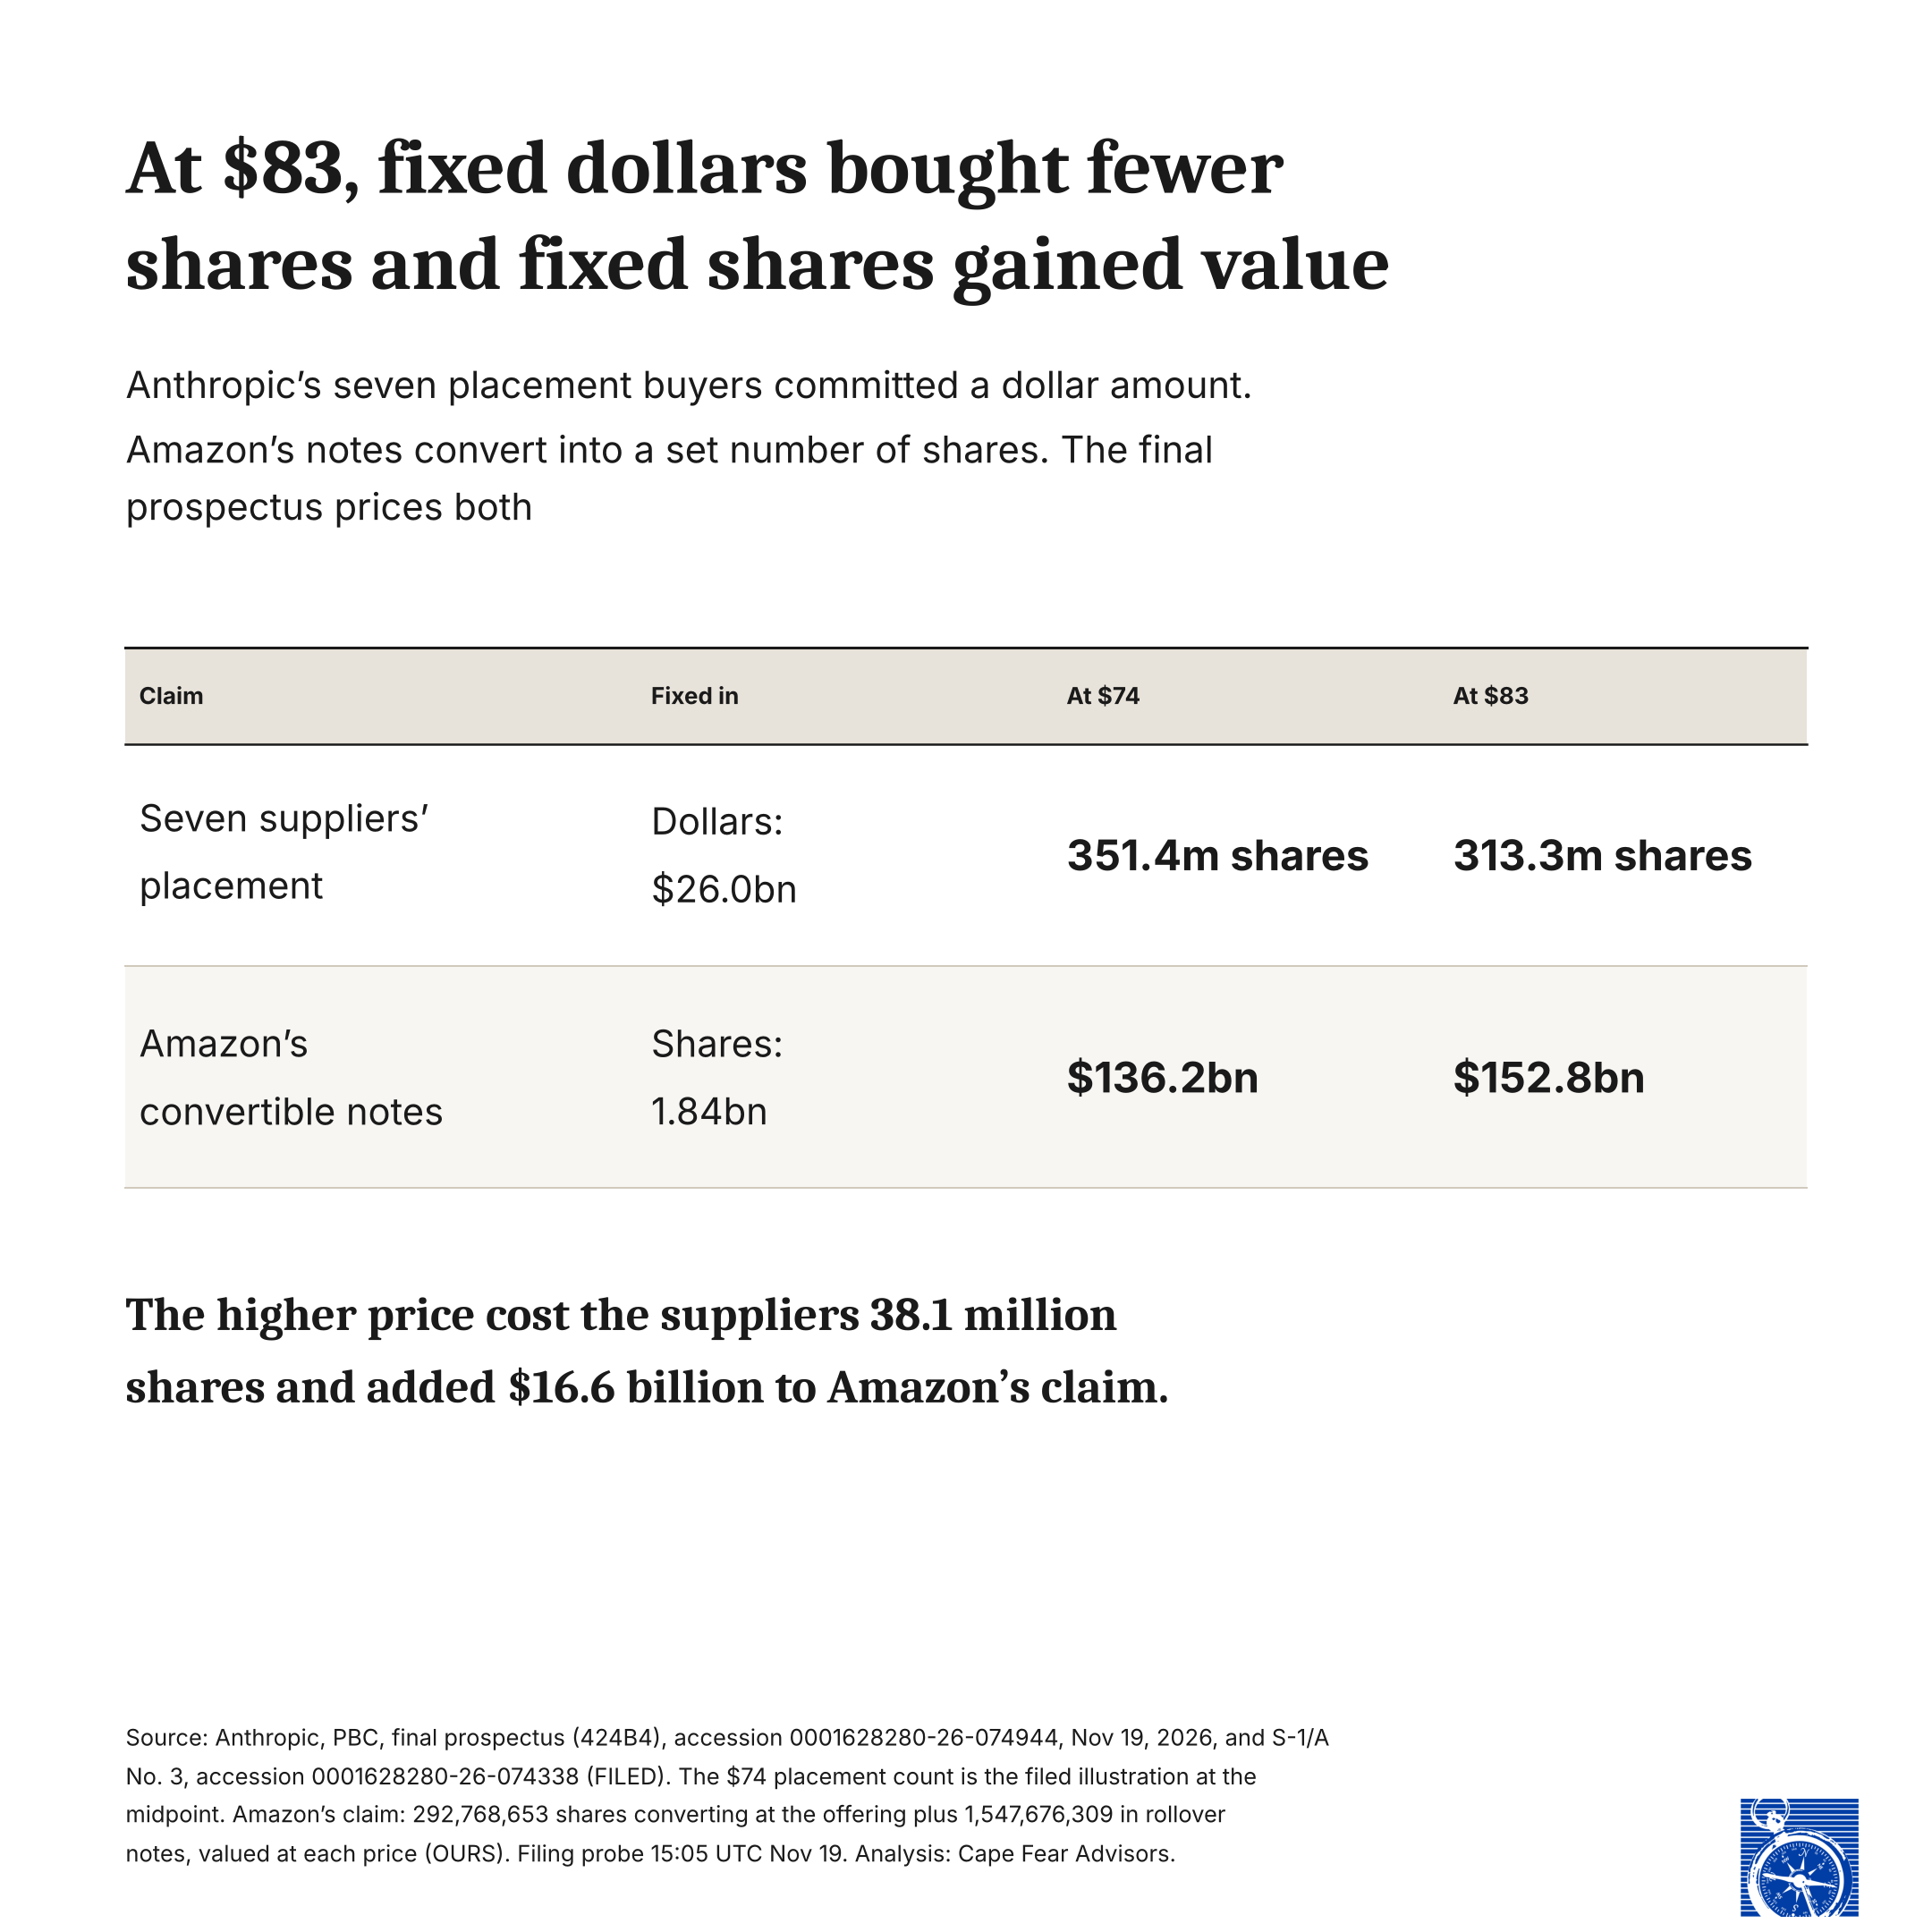
Seven of the companies Anthropic buys from agreed to put $26.0 billion into its stock at whatever price the offering set. Amazon's route in was fixed years earlier, as convertible notes that turn into a set number of shares. On Wednesday night the price came in at $83, above the $70 to $78 range, and the final prospectus filed on Thursday morning shows what each arrangement bought. (1)
The two kinds of claim moved in opposite directions. At $83, the suppliers' $26.0 billion buys 313,253,007 shares, 38,098,341 fewer than at the $74 midpoint, while Amazon's 1.84 billion share claim comes to about $152.8 billion, about $16.6 billion more than at the midpoint. (2)
The counts, as promised
On November 10 we said we would print the valuation at pricing on both counts, with the price beside each. The final prospectus now supplies both counts itself.
Outstanding after the offering and the placement: 13,219,642,276 shares. At $83, that is about $1.10 trillion. The count includes the 846,840,960 shares contributed to the Public Benefit Fund, which are "legally outstanding" but, held by a wholly owned subsidiary, "not considered outstanding for accounting purposes." On that accounting basis the count is 12,372,801,316, about $1.03 trillion. If the underwriters exercise their option in full, the count is 13,366,642,276, about $1.11 trillion. (3)
The prospectus also tabulates every further share its plans and instruments can issue: options net of the treasury method, unvested units, Amazon's rollover notes, the donation match obligation already vested, and shares held back from acquisitions. By our sum, its table comes to 18,137,587,875 shares. At $83, that is about $1.51 trillion, which matches the "around $1.5 trillion" in the headlines. (4)
The widest count is 37 percent above the filed one. The price is 12 percent above the midpoint. The count still moves the answer more than the price. Our Note on Wednesday night, written before the final prospectus, put the filed count at 13.09 billion and the gap at 38 percent; the upsizing added shares, and the figures above replace it. (5)
Seven buyers, one price
Each supplier signed for a dollar amount at the offering price, "severally and not jointly." The price set the share count:
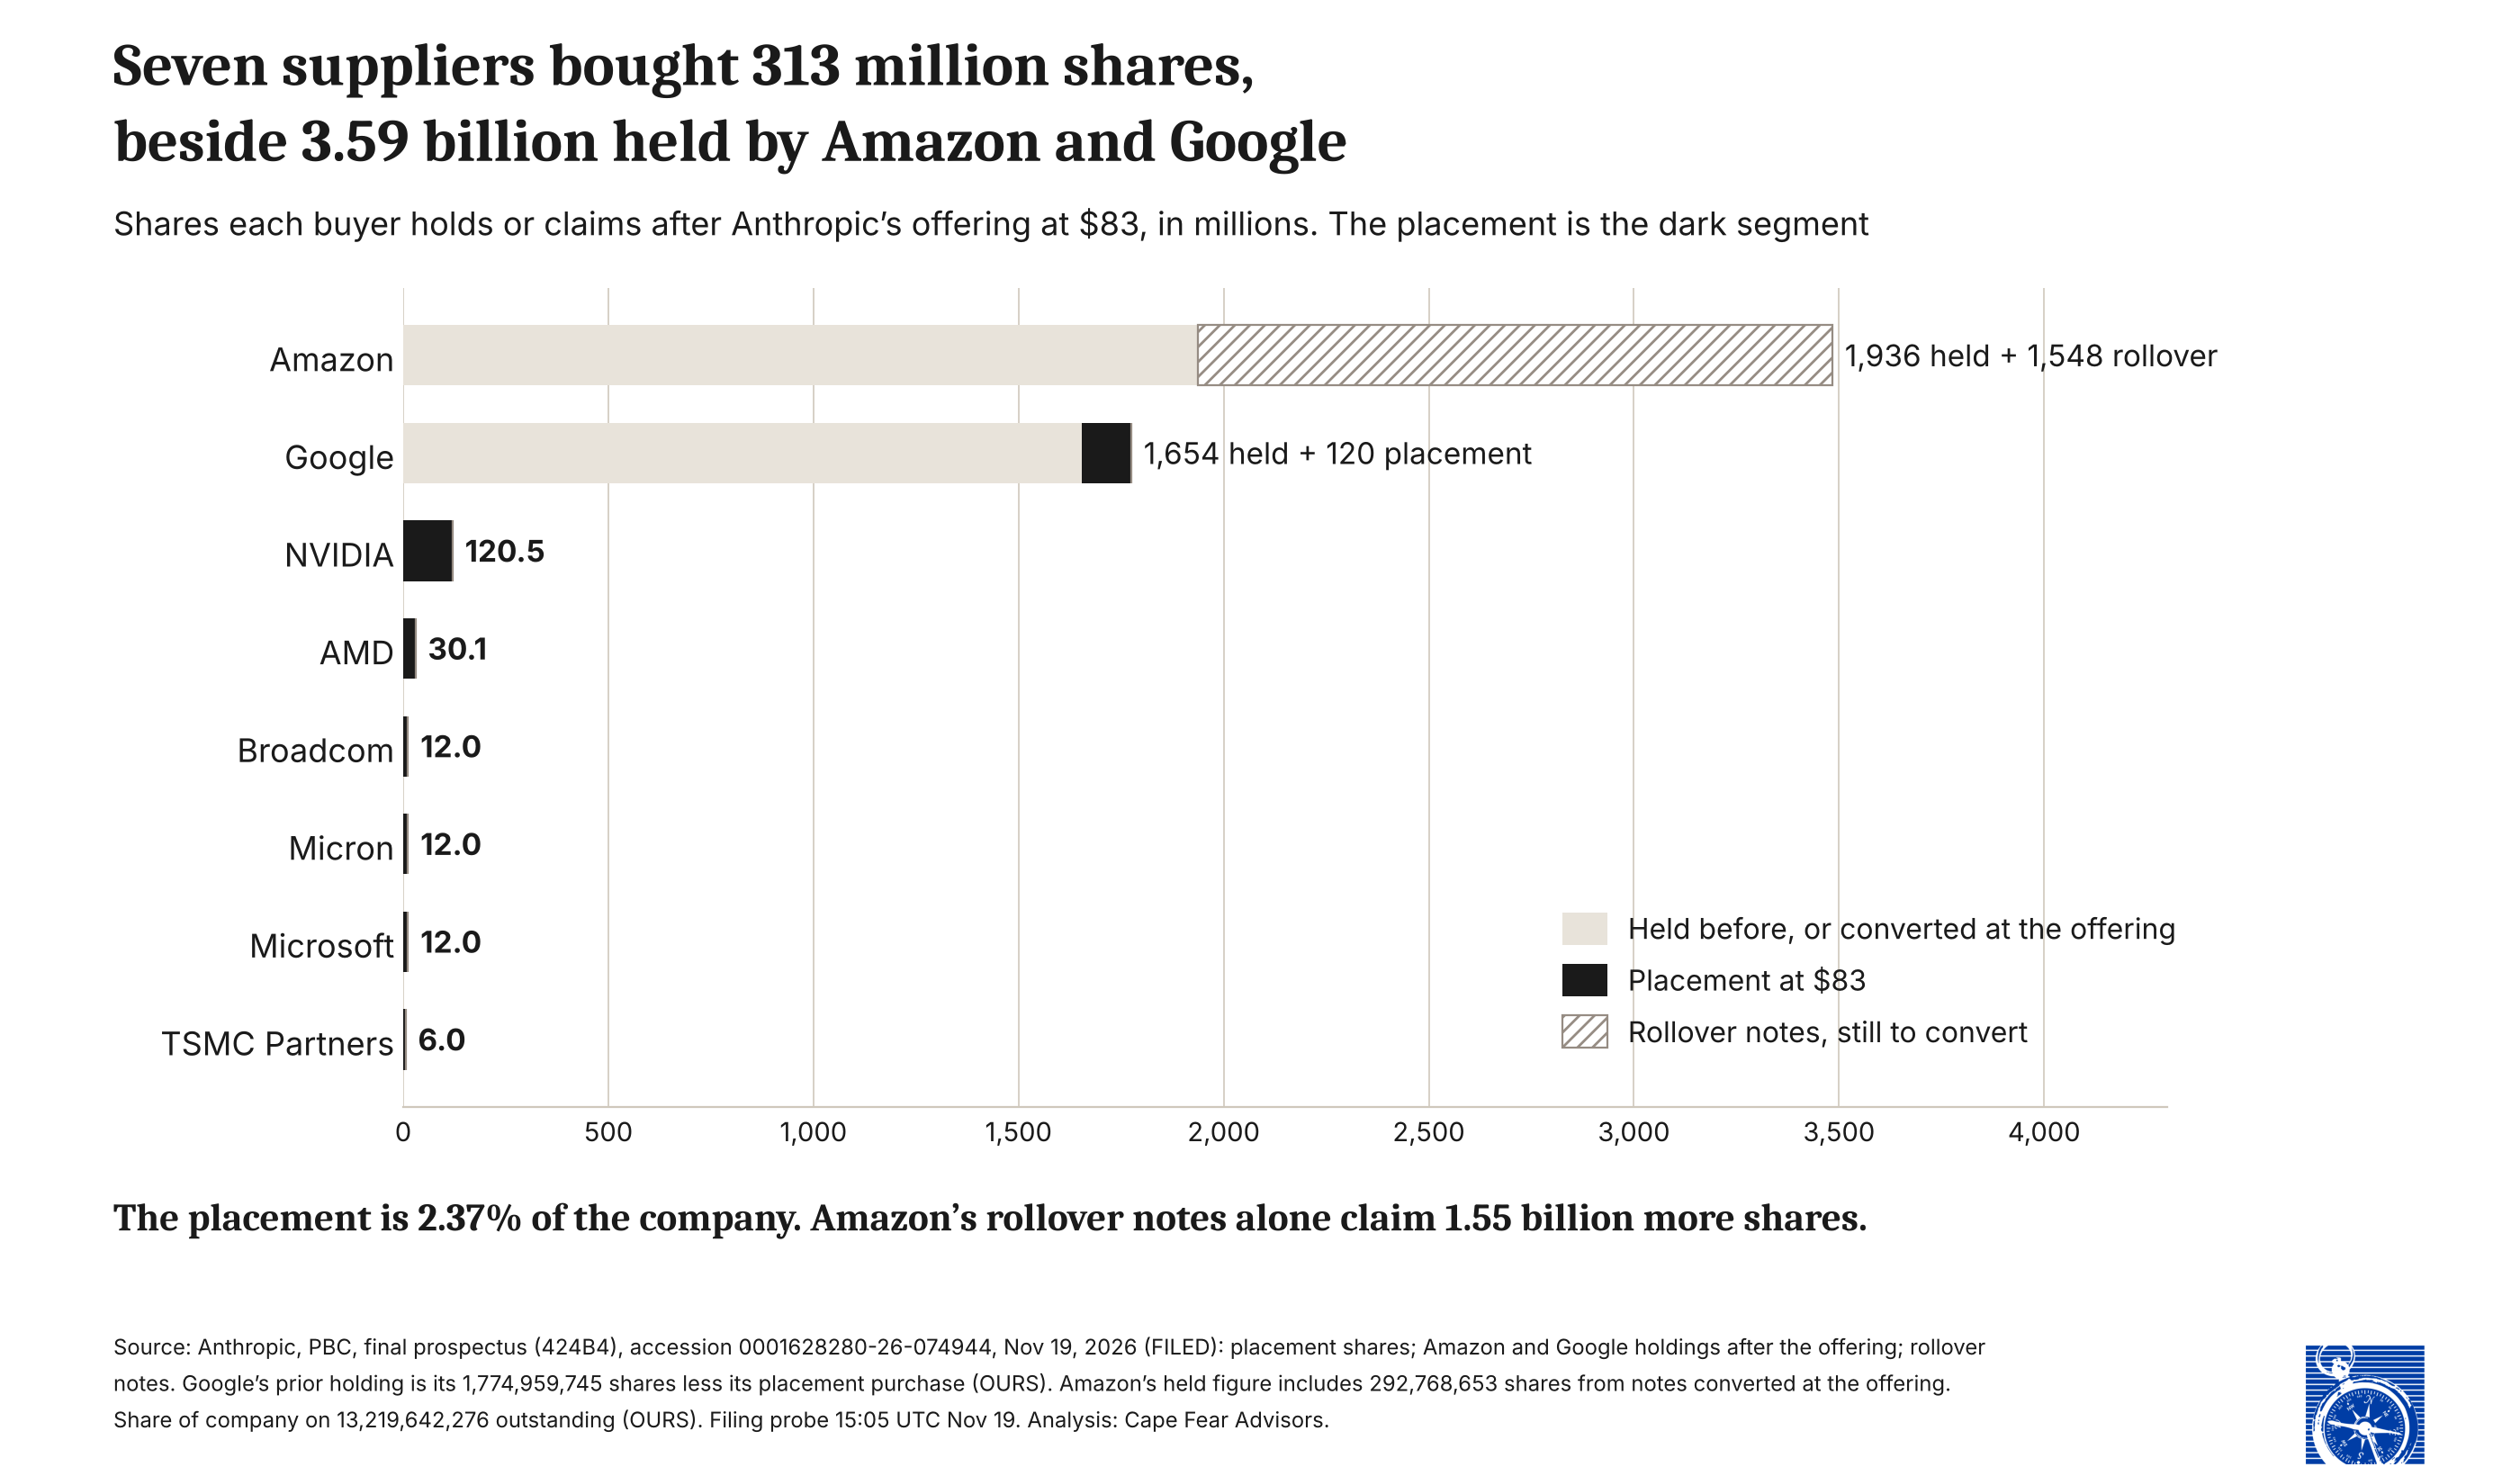
- Google: $10.0 billion for 120,481,927 shares. The prospectus calls the purchase "its exercise in full of its option" under the 2026 note purchase agreement. With the shares it already held, Google owns 1,774,959,745, or 13.4 percent of the company. (6)
- NVIDIA: $10.0 billion for 120,481,927 shares, 0.91 percent. NVIDIA's 10-Q for the quarter to October 2025 carried an "agreement, subject to certain closing conditions, to invest up to $10 billion in Anthropic." The link between that agreement and this purchase is ours. (7)
- AMD: $2.5 billion for 30,120,481 shares. The purchase "will satisfy a portion of its commitment" to buy Anthropic stock under the July hardware supply agreement, which carries up to $5.0 billion of equity commitments. (8)
- Broadcom, Micron and Microsoft: $1.0 billion each, for 12,048,192 shares each. Broadcom is the lessor under the 2026 Lease Arrangement, with rent of about $125.2 billion over five years. Microsoft is owed at least $47.2 billion through June 2033. Micron appears in the risk factors as one of three makers of high-bandwidth memory. (9)
- TSMC Partners: $500 million for 6,024,096 shares. TSMC appears as the foundry behind Anthropic's Taiwan concentration, also in the risk factors. (10)
The placement shares together are 2.37 percent of the company. Each buyer pays the public price, and Anthropic pays no underwriting discount on the placement, against $0.56122 a share on the offering. (11)
NVIDIA's purchase equals half of the $20 billion of equity investment commitments NVIDIA reported on Tuesday. Whether the $10 billion sits inside the $20 billion, NVIDIA's results documents leave unstated. Its 10-Q, due by December 4, covers the quarter before the purchase closed, so whether it describes the purchase as a subsequent event is NVIDIA's judgment of materiality. (12)
Amazon, by the share
Amazon is outside the placement and holds the larger claim. Its convertible notes carry $6.2 billion of principal and convert into a fixed count, 1,840,444,962 Class N shares, about $3.37 a share. The rollover notes convert at the lowest of that price, the offering price and a 10-day average, so the count holds while the stock trades above it. A 12 percent ownership cap limits how many convert at any moment, and "Amazon has elected not to waive" it. (13)
At the offering, 292,768,653 shares convert. The remaining 1,547,676,309 become rollover notes, converting at each quarter end as room under the cap opens, or repaid in cash at maturity. With its preferred stock converted at the offering, Amazon holds 1,936,452,353 shares after the offering, 14.6 percent of the company; uncapped, the filing puts its holding at 23.6 percent. (14)
The share count is what moved with the price. On November 13 we set the two marks on these notes against the range: Amazon carried them at $146.2 billion, about $79.44 a share, and Anthropic at $130.5 billion, about $70.91. The range sat between the two. At $83, the claim comes to about $152.8 billion, above both marks: about $6.6 billion above Amazon's and about $22.3 billion above Anthropic's. (15)
Each side books that move its own way. Anthropic carries the notes as a liability at fair value and charges increases to its results; Amazon carries them as available for sale, with gains held in other comprehensive income. The rollover notes stay on both books until they convert, and each quarter's reports now mark them against a listed price. (16)
When each trade closes, and where to check it
The placement closes "immediately subsequent to" the offering, subject to conditions "including the receipt of the requisite approval of our stockholders, which we have obtained." The last four words are new in the final prospectus. The offering itself stands alone: "The completion of this offering is not contingent on the completion of the concurrent private placement." (17)
The placement shares are restricted securities and carry no lock-up: they "will not be subject to market standoff agreements with us or lock-up agreements with the underwriters." Resale runs through registration or an exemption such as Rule 144, and Google's shares carry registration rights. The public offering's insiders and early holders follow the release schedule set out in the prospectus. (18)
Each buyer reports its side in its own filing, on its own calendar:
- NVIDIA: the 10-Q for the quarter to October 25, due by December 4, for the equity commitments line; any description of the purchase itself falls to subsequent events, as NVIDIA judges materiality.
- Alphabet, Microsoft, AMD, Broadcom and Micron: their next 10-Q or 10-K. Alphabet's filings have so far described Anthropic as "a private company."
- TSMC: its reports as a foreign private issuer.
- Amazon: its 10-K for 2026, for the notes at fair value and the converted shares.
- Anthropic: its first quarterly report as a listed company, for the rollover conversions and the revaluation. (19)
The rating the cash meets
Anthropic leaves the offering with $232.4 billion of cash and short-term investments, pro forma, against $70.7 billion of compute commitments due in the twelve months after September 30. The underwriters also hold an option on 147,000,000 more shares, all from the company and carrying no discount; exercised in full, it lifts net proceeds, the placement included, from about $104.8 billion to about $117.0 billion. (20)
Moody's, S&P and Fitch have yet to rate Anthropic. KBRA gave it an issuer rating of BB+ in June, one notch below investment grade, the Financial Times reported, and Blackstone told investors to expect a "high" junk rating from the major agencies after the offering, according to the same paper. (21)
The prospectus names the line where a rating binds. Anthropic's $15.0 billion revolver is secured by substantially all of its assets until it has "obtained an Investment Grade Rating... from at least two out of three of Moody's, S&P, and Fitch." From that point, at Anthropic's election, the guarantees and liens are released and the pricing moves to a ratings grid. (22)
SpaceX cleared that line in June, with investment-grade ratings from all three: Baa1 at Moody's, BBB+ at Fitch and BBB at S&P. Fitch's rationale, as reported, cites management's targets of 2 to 3 times gross leverage and "a minimum cash balance of $25 billion, with no plans for shareholder distributions," alongside more than $90 billion of pro forma liquidity. Anthropic now holds cash on a larger scale. Fitch also said the concentration of control in one person "constrains the rating by two notches relative to the level otherwise supported" by SpaceX's operating and financial profile. Anthropic files as a "controlled company": its Long-Term Benefit Trust elects a majority of the board, and a company owned by its seven co-founders holds stock carrying 50.1 percent of the vote on other matters. A cash policy of the same kind is Anthropic's to offer, and the first agency rationale will show both whether it did and how the agency weighed the governance. (23)
The rating reaches past Anthropic's own balance sheet. The junior debt behind its Broadcom-backed chip leases carries Anthropic's credit, rated BB+ and priced from about 8.5 percent to above 10 percent, by the reported figures. Some of its newest compute contracts depend on "the counterparty's ability to secure financing." At Riot's Corsicana campus, Anthropic fronts up to $4.0 million a megawatt of module costs, repaid in cash if Riot finds financing "on market terms reasonably acceptable to it," and otherwise in rent credits at 12 percent a year. A rating from two of the three, in either direction, bears on each of those layers. (24)
NVIDIA sits on both sides of the line. Its extended payment terms go to "certain investment-grade customers," and Colette Kress, its interim chief executive and finance chief, said on Tuesday's call that such customers "can be very helpful." Its route to Anthropic runs one step out: the compute "powered by NVIDIA GPUs" that SpaceXAI, Nscale and Lambda sell Anthropic, and now $10 billion of Anthropic's stock. NVIDIA's disclosure screens its longer terms on investment grade; its equity went to a company whose only issuer rating, KBRA's BB+, is speculative grade. (25)
The first of the filings above is NVIDIA's 10-Q. The first event that can reprice the rest is a rating.
Free to read, no paywall. Readers who find the work useful can support it at the foot of the page; payment offsets the time and buys no access. Corrections run in daylight, dated, in a comment or in the following piece, and a reader who finds one is doing us a favor.
Standing Disclosure
Cape Fear Advisors holds no direct position, long or short, in the securities discussed here. Any exposure is indirect, through managed funds it does not control, which may include index funds holding the public companies named.
Anthropic, a subject of our coverage, is the developer of Claude, which we use in preparing our work. That nearness cannot be checked away, which is why no claim here rests on trust in the tool: every figure carries a public source and every derived figure carries its inputs in the notes. Figures are quoted from the filers without characterization, and the same standard of reading is applied to every filer named. The author's operating business works in advertising measurement.
Notes
[1] FILED. Anthropic, PBC, final prospectus under Rule 424(b)(4), accession 0001628280-26-074944, accepted November 19, 2026 at 11:05 UTC. Pricing free writing prospectus, accession 0001628280-26-074937, November 19 at 02:33 UTC. Registration statement under Rule 462(b) (Form S-1MEF), accession 0001628280-26-074904, November 18, registering 178,250,000 additional shares: 155,000,000 of upsizing and 23,250,000 of growth in the underwriters' option, from 123,750,000 to 147,000,000 (OURS: 825,000,000 + 155,000,000 = 980,000,000). Offering: 980,000,000 shares of Class A common stock at $83.00, of which 956,351,354 by the company and 23,648,646 by selling stockholders; underwriters' option 147,000,000 shares. Prior range: $70.00 to $78.00 on 825,000,000 shares (S-1/A No. 3, accession 0001628280-26-074338).
[2] FILED: 424B4, Concurrent Private Placement: 313,253,007 Class N shares at $83.00 for an aggregate of $26.0 billion. FILED: S-1/A No. 3, Capitalization and dilution tables at the assumed $74.00: 351,351,348 Class N shares in the placement. OURS: 351,351,348 less 313,253,007 = 38,098,341. FILED: 424B4: 292,768,653 shares on conversion plus 1,547,676,309 rollover = 1,840,444,962 (OURS, the sum, which equals the uncapped count in S-1/A No. 2). OURS: 1,840,444,962 × $83 = $152.76 billion; × $74, the filed midpoint, = $136.19 billion; difference $16.56 billion. The $74 figures are references at the filed midpoint; both trades close at $83.
[3] FILED: 424B4, The Offering: "13,219,642,276 shares (or 13,366,642,276 shares if the underwriters exercise their option...)"; the Initial Public Benefit Issuance, "the shares of which (i) are considered legally outstanding, (ii) are not considered outstanding for accounting purposes while held by our wholly owned subsidiary." OURS: 13,219,642,276 less the 12,372,801,316 in the share table's pro forma totals equals 846,840,960, the fund's shares; 13,219,642,276 × $83 = $1,097.2 billion; 12,372,801,316 × $83 = $1,026.9 billion.
[4] FILED: 424B4, the share table following The Offering, "Additional Adjustments": RSUs granted after September 30, 2026, 47,041,287; shares issued under the treasury stock method, (62,208,882); rollover notes, 1,547,676,309; acquisition issuances, 561,963 and 848,882; acquisition holdback shares, 1,590,190; Matching Issuance, 27,991,850; Vested Matching Obligation, 553,441,297; Initial Public Benefit Issuance, 846,840,960. Column totals: Class A 7,585,256,149; Class N 7,766,496,616; stock options 1,712,133,811; RSUs 1,073,701,297; Class T and F, 2. OURS: the sum, 18,137,587,875, which equals the 13,219,642,276 outstanding plus the adjustments, the fund's shares counted once; × $83 = $1,505.4 billion. The prospectus itself states no total and no valuation. REPORTED: The Wall Street Journal, Corrie Driebusch and Kate Clark, "Anthropic Prices IPO at $83 a Share on Strong Demand," updated November 18, 2026, 4:53 pm ET ("around $1.5 trillion" on a fully diluted basis).
[5] OURS: 18,137,587,875 / 13,219,642,276 = 1.372, floored to 37 percent; $83 / $74 = 1.122, floored to 12 percent. Correction carried: the Note of November 18 used 13,086,672,593 shares (S-1/A No. 3, on the $74 assumptions, before the upsizing), giving about $1.09 trillion and 38 percent. The final count gives about $1.10 trillion and 37 percent. Same conclusion; the Note stands as posted.
[6] FILED: 424B4, Concurrent Private Placement ("Google's purchase in the concurrent private placement constitutes its exercise in full of its option under the Google 2026 NPA... and will reduce the remaining amount available under the Google 2026 NPA") and Prospectus Summary, Certain stockholders (Google LLC 1,774,959,745 Class N shares, 13.4 percent of outstanding capital stock).
[7] FILED: NVIDIA Corporation Form 10-Q for the quarter ended October 26, 2025, accession 0001045810-25-000230. FILED: 424B4: NVIDIA 120,481,927 shares for approximately $10.0 billion. OURS: 120,481,927 / 13,219,642,276 = 0.91 percent; the link between the two documents.
[8] FILED: 424B4, Concurrent Private Placement; Liquidity and Capital Resources, AMD Agreement ("up to $5.0 billion in equity commitments").
[9] FILED: 424B4: Broadcom, Micron and Microsoft, 12,048,192 shares each for approximately $1.0 billion; 2026 Lease Arrangement, "rent payments over the five-year equipment lease are equal to an aggregate of approximately $125.2 billion"; Microsoft, "at least $47.2 billion and up to $49.2 billion between November 2026 and June 2033." The identification of Broadcom as lessor under the 2026 Lease Arrangement follows S-1/A No. 2, as read in our November 13 piece.
[10] FILED: 424B4: TSMC Partners, Ltd., 6,024,096 shares for approximately $500 million. Risk Factors: high-bandwidth memory is "largely manufactured by SK hynix Inc., Samsung Electronics Co., and Micron Technology, Inc."; the most advanced chip manufacturing capacity is concentrated "primarily at Taiwan Semiconductor Manufacturing Company."
[11] FILED: 424B4 cover: underwriting discount $0.56122 per share, $550,000,000 in total; "We will receive all of the proceeds from, and will not pay any underwriting discounts or commissions with respect to, the shares that are sold in the concurrent private placement." OURS: 313,253,007 / 13,219,642,276 = 2.37 percent.
[12] FURNISHED: NVIDIA Form 8-K, accession 0001045810-26-000088, November 17, 2026, CFO commentary: equity investment commitments of $20 billion at October 25, 2026. FILED: NVIDIA Form 10-Q for the quarter ended July 26, 2026, accession 0001045810-26-000075: $25 billion. OURS: $10.0 billion / $20 billion = 0.5. The comparison is arithmetic only.
[13] FILED: 424B4, Risk Factors and Liquidity and Capital Resources, Convertible Notes ("which Amazon has elected not to waive in connection with this offering"). FILED: S-1/A No. 2: rollover notes convert at the lowest of the fixed conversion price, the offering price and a 10-day volume-weighted average price. FILED: S-1/A No. 2, accession 0001628280-26-072484: principal $6,203 million; 1,840,444,962 Class N shares issuable before the cap. OURS: $6,203 million / 1,840,444,962 = $3.37.
[14] FILED: 424B4: Convertible Notes Conversion, 292,768,653; rollover notes, 1,547,676,309; rollover notes "will automatically convert, subject to Amazon's ownership cap, into shares of our Class N common stock at the applicable conversion price at the end of each fiscal quarter following this offering," or are "repaid in cash at such maturity date"; Amazon "will hold 1,936,452,353" Class N shares, "14.6%... of our outstanding capital stock," and uncapped "3,484,128,662 shares... 23.6% of our outstanding capital stock." In S-1/A No. 3, at $74 on the smaller offering, the split was 276,827,518 and 1,563,617,444. FILED: Amazon 10-Q per note 15: "we held 164 million shares of Anthropic nonvoting preferred stock" at September 30, 2026, each "convertible into ten shares of nonvoting common stock." OURS: 1,936,452,353 less 292,768,653 = 1,643,683,700, or 164,368,370 preferred shares before conversion, which the 10-Q states to the nearest million.
[15] FILED: Amazon.com Form 10-Q for the quarter ended September 30, 2026, accession 0001018724-26-000040: notes at fair value $146.2 billion. FILED: S-1/A No. 2: convertible notes at fair value $130,502 million at September 30, 2026. OURS, as published November 13: $146.2 billion / 1,840,444,962 = $79.44; $130.502 billion / 1,840,444,962 = $70.91. OURS: $152.76 less $146.2 = $6.56 billion; $152.76 less $130.50 = $22.25 billion.
[16] FILED: S-1/A No. 2 (fair value option; "changes in the fair value of convertible notes" in other income); Amazon 10-Q per note 15 (notes "classified as available-for-sale and reported at fair value," unrealized gains in accumulated other comprehensive income). The fourth-quarter amounts are unreported as of this piece.
[17] FILED: 424B4, Concurrent Private Placement. FILED: S-1/A No. 2 and No. 3 carry "including the receipt of the requisite approval of our stockholders" without "which we have obtained" (text search, local copies, November 19).
[18] FILED: 424B4, Concurrent Private Placement and Shares Eligible for Future Sale. The same lock-up sentence appears in S-1/A No. 2 and No. 3.
[19] OURS: the calendar. NVIDIA's due date: 40 days after the October 25 quarter end. FILED: Alphabet Inc. Form 10-Q for the quarter ended September 30, 2026, "a private company," as read in our November 13 piece.
[20] FILED: 424B4, Summary Consolidated Balance Sheet Data: cash, cash equivalents, and short-term investments $131,845 million actual, $232,351 million pro forma as adjusted; Liquidity and Capital Resources: "Approximately $70.7 billion of these commitments are due in the 12 months following September 30, 2026"; underwriters' option, 147,000,000 shares of Class A common stock from the company; cover: "The underwriters will not receive any discount or commission on any shares of our Class A common stock sold pursuant to their option to purchase additional shares"; Use of Proceeds: "approximately $104.8 billion (or approximately $117.0 billion if the underwriters' option... is exercised in full)." Probe: no exercise filed as of 15:27 UTC, November 19.
[21] REPORTED: Financial Times, Michelle Chan, Rafe Rosner-Uddin and George Hammond, "Anthropic assigned highest junk credit rating in June," October 16, 2026 (KBRA issuer rating of BB+ in June, "one notch below investment grade"; Moody's, S&P and Fitch "will ultimately determine Anthropic's post-IPO credit status"); Financial Times, Michelle Chan and George Hammond, "Anthropic may not secure investment-grade rating after IPO, Blackstone tells investors," October 30, 2026 (Blackstone's expectation of a "high" junk rating; "a rating in the double-B range or above is more likely"; the big three "have not officially issued any credit ratings for Anthropic"). Both read at source, November 19. A news search at 15:28 UTC, November 19, found no rating from Moody's, S&P or Fitch.
[22] FILED: 424B4, Liquidity and Capital Resources, A&R Credit Agreement: a $15.0 billion senior secured revolving credit facility maturing September 4, 2031, secured "by substantially all of our assets"; release "on and after the date we have obtained an Investment Grade Rating (as defined in the A&R Credit Agreement) from at least two out of three of Moody's, S&P, and Fitch, at our election"; thereafter "such applicable margin will vary depending on our credit ratings." Minimum liquidity of $5.0 billion from the quarter ending December 31, 2026.
[23] REPORTED: Euronews, June 19, 2026, and Investing.com, "Fitch assigns BBB+ rating to SpaceX with stable outlook," June 18, 2026 (Moody's Baa1, Fitch BBB+, S&P BBB, each stable). Fitch's rationale as reported by Investing.com: "SpaceX targets 2x-3x gross EBITDA leverage and a minimum cash balance of $25 billion, with no plans for shareholder distributions"; "The company holds over $90 billion in pro forma liquidity"; the concentration of voting control and executive authority "constrains the rating by two notches relative to the level otherwise supported by SpaceX's operating and financial profile." Fitch's own release could not be retrieved (site refused automated access, November 19); the targets are management's, stated to the agency, and appear in no SEC filing. FILED: 424B4, Controlled Company Status ("because the LTBT, as the sole holder of our Class T common stock, generally has the power to elect a majority of the authorized members of our board of directors"); Class F common stock held by the Founder LLC, whose sole members are the seven co-founders, "entitled to an aggregate number of votes that equals 50.1% of the total voting power... including the election of our directors other than the Class T directors."
[24] REPORTED: Financial Times, October 16, 2026: about $4.4 billion of junior debt in the June $35 billion package, rated BB+ stable by KBRA, "sold with a yield of about 8.5 per cent"; Financial Times, October 30, 2026: North Star's $18 billion of junior debt, BB+ with positive outlook from KBRA and BB from Morningstar DBRS, with Blackstone funds holding $9 billion "at a lucrative yield of more than 10 per cent." Both read at source. FILED: 424B4, subsequent events: arrangements "subject to contingent conditions prior to commencement, such as the counterparty's ability to secure financing, facilities, or regulatory approvals." FILED: Riot Platforms, Inc. Form 10-Q for the quarter ended September 30, 2026, accession 0001104659-26-122417: the Corsicana Lease with "Anthropic PBC (the 'Frontier AI Lab')," effective November 4, 2026; reimbursement "of up to $4.0 million per MW of critical IT power actually achieved, subject to Riot Corsicana obtaining financing on market terms reasonably acceptable to it," otherwise "rent credits that amortize that amount, plus interest at 12% per year." OURS: the reach of Anthropic's rating to the Riot lease runs through Riot's financing; the filing ties the reimbursement to Riot's financing terms and names Anthropic as tenant, and the bearing of the rating on those terms is our reading.
[25] FURNISHED: NVIDIA Form 8-K, accession 0001045810-26-000088, CFO commentary ("extended payment terms on large, multi-quarter agreements with certain investment-grade customers"). REPORTED: NVIDIA third-quarter call, November 17, 2026, transcripts (singjupost; stockanalysis; MarketWatch citing FactSet): "Those IG customers can be very helpful, particularly when it comes to enabling the amount of money that is required." FILED: 424B4: SpaceXAI, Nscale and Lambda agreements "to access compute powered by NVIDIA GPUs." The KBRA issuer rating per note 21; Morningstar DBRS rates a North Star tranche, per note 24.
Probes. EDGAR, Anthropic, NVIDIA, Nscale, Amazon, SpaceX and Tesla dockets, 15:27 UTC November 19, 2026: Anthropic latest 424B4 (11:05 UTC), pricing FWP, S-8s, Forms 3; no exercise of the option. NVIDIA latest 8-K November 17; no 10-Q. Nscale latest S-1/A November 12. SpaceX latest Schedule 13G/A November 16. Tesla latest DEFA14A November 18. Re-run within the hour before publication.
Analysis: Cape Fear Advisors.
This piece also appears on Substack. Cape Fear Advisors is an independent advisory firm based in Portsmouth, NH.
Contact Cape Fear Advisors